Transition profit spreading and tax-year apportionment for sole traders and partners
Secure checkout. Your file is ready in your client portal as soon as payment clears.
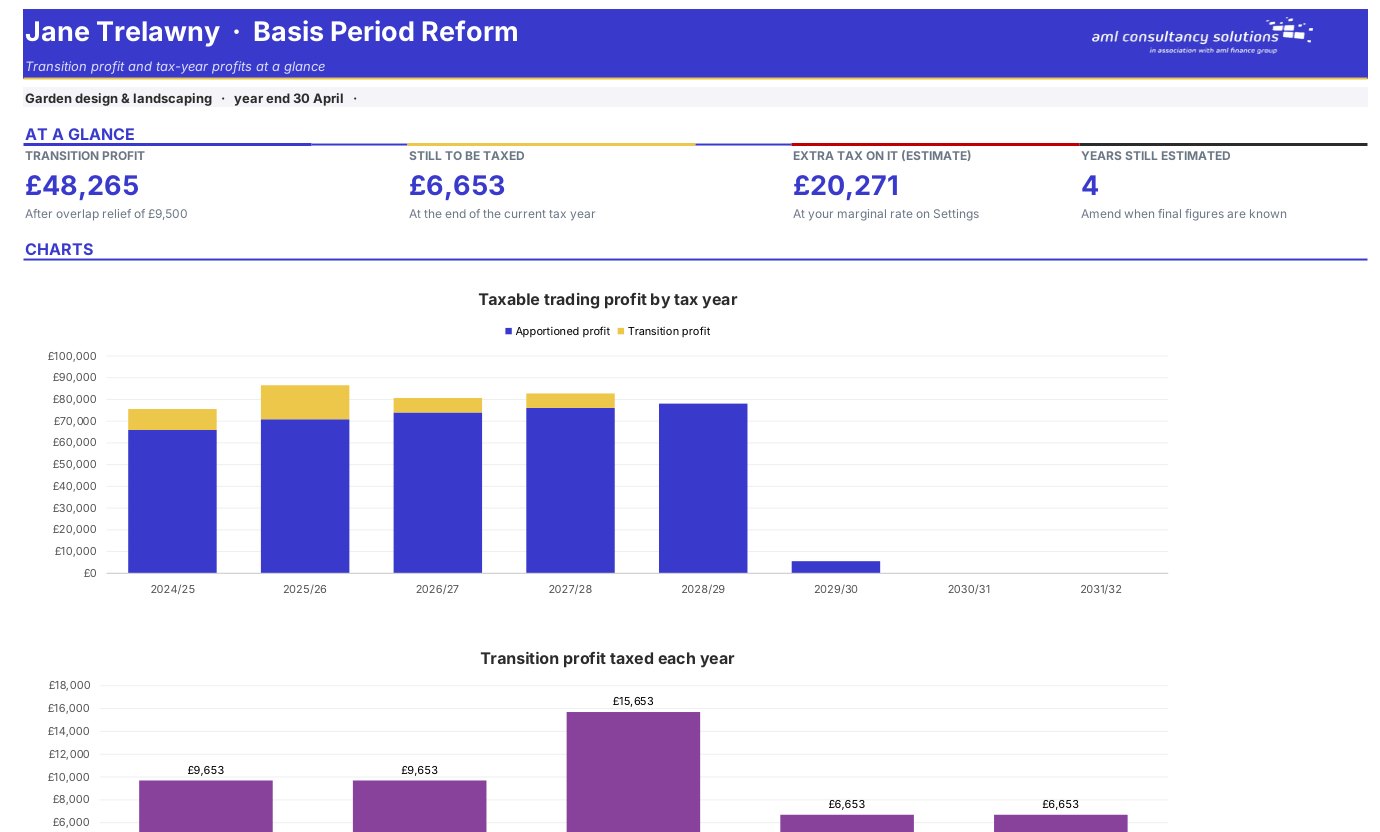
Basis period reform moved every self-employed person and partner onto the tax year basis from 2024/25. If your accounting year does not end on 31 March or 5 April, 2023/24 created an extra "transition profit", which is taxed over five years unless you choose to speed it up – and you now have to apportion two sets of accounts to each tax year, often using estimates. This tracker works out the transition profit and overlap relief, spreads it over 2023/24 to 2027/28 with any acceleration you choose, and apportions your accounts profits to each tax year, flagging where an estimate needs to be replaced with the final figure.
See how it works
The sheets you will use most, in the order you will use them – shown with the sample data every workbook comes with.
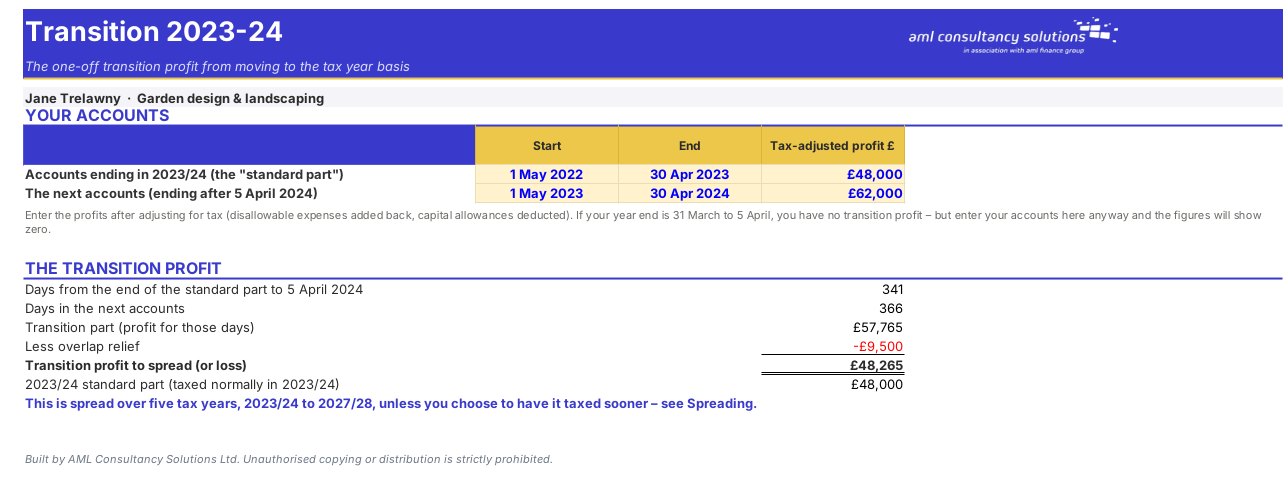
Step 1
The standard part, transition part and overlap relief for 2023/24. What you do: enter the accounts figures.
Step 2
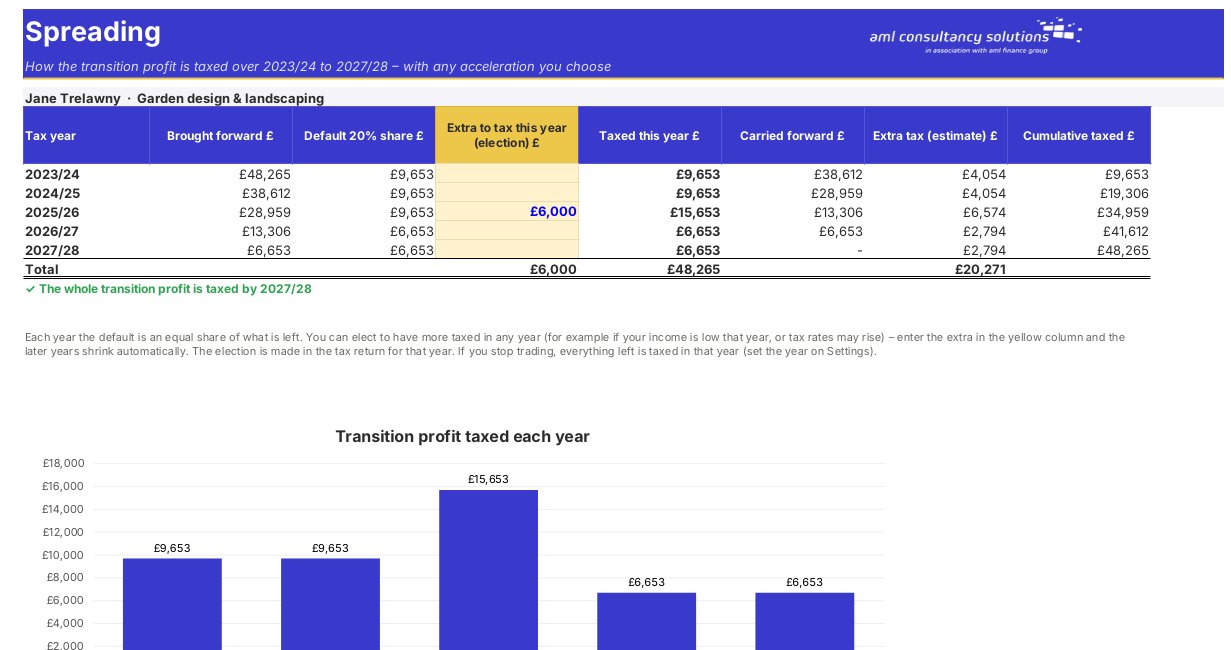
Transition profit taxed in each year from 2023/24 to 2027/28. What you do: enter any amount you choose to accelerate.
Step 3
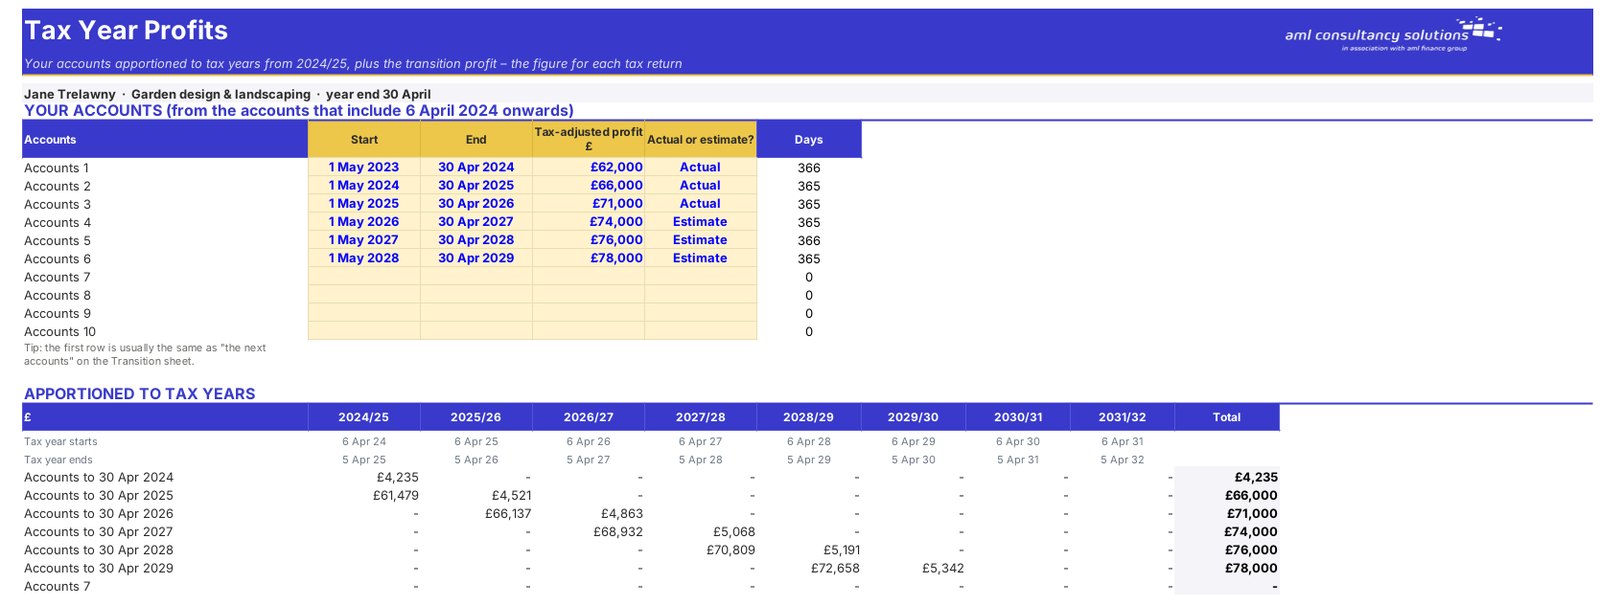
Accounts profits apportioned to each tax year. What you do: enter each year's profit and whether it is final.
Step 4
Who it is for
Quick start
Your file is only released to your client portal once payment has cleared.
You are taken to our secure checkout.
Checkout takes a minute and you get a receipt by email.
Your file is ready in your client portal as soon as payment clears, and we email you your invoice with a link to the portal.
We can adapt any prebuilt solution or build something bespoke, with a lifetime bug-free guarantee.
Part of AML Finance Group
Our sister firm, AML Accountancy Solutions, is an award-winning accountancy practice helping businesses and individuals across the UK with their accounts, tax, bookkeeping and payroll.
Visit AML Accountancy Solutions