Which way of working out your profit suits your business – and what it does to your tax bill
Secure checkout. Your download link is sent as soon as payment clears.
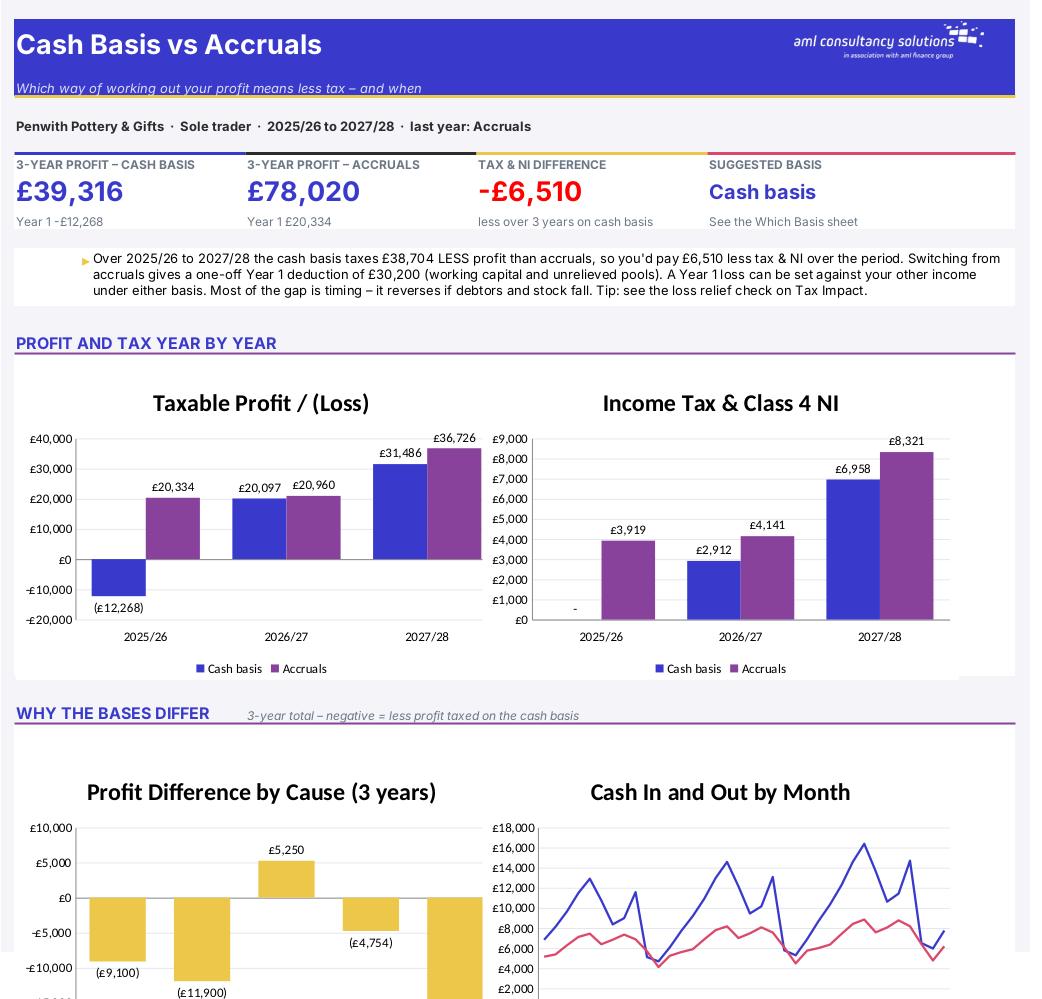
Sole traders and partnerships can work out their taxable profit in two ways. The cash basis counts money when it actually comes in and goes out. Accruals (traditional accounting) counts income when it is earned and costs when they are incurred – so it adjusts for unpaid invoices, unpaid bills and stock. Since the 2024/25 tax year the cash basis has been the default for every sole trader and partnership, with no turnover limit. If you'd rather use accruals you have to opt out on your tax return.
See how it works
The sheets you will use most, in the order you will use them – shown with the sample data every workbook comes with.
Step 1
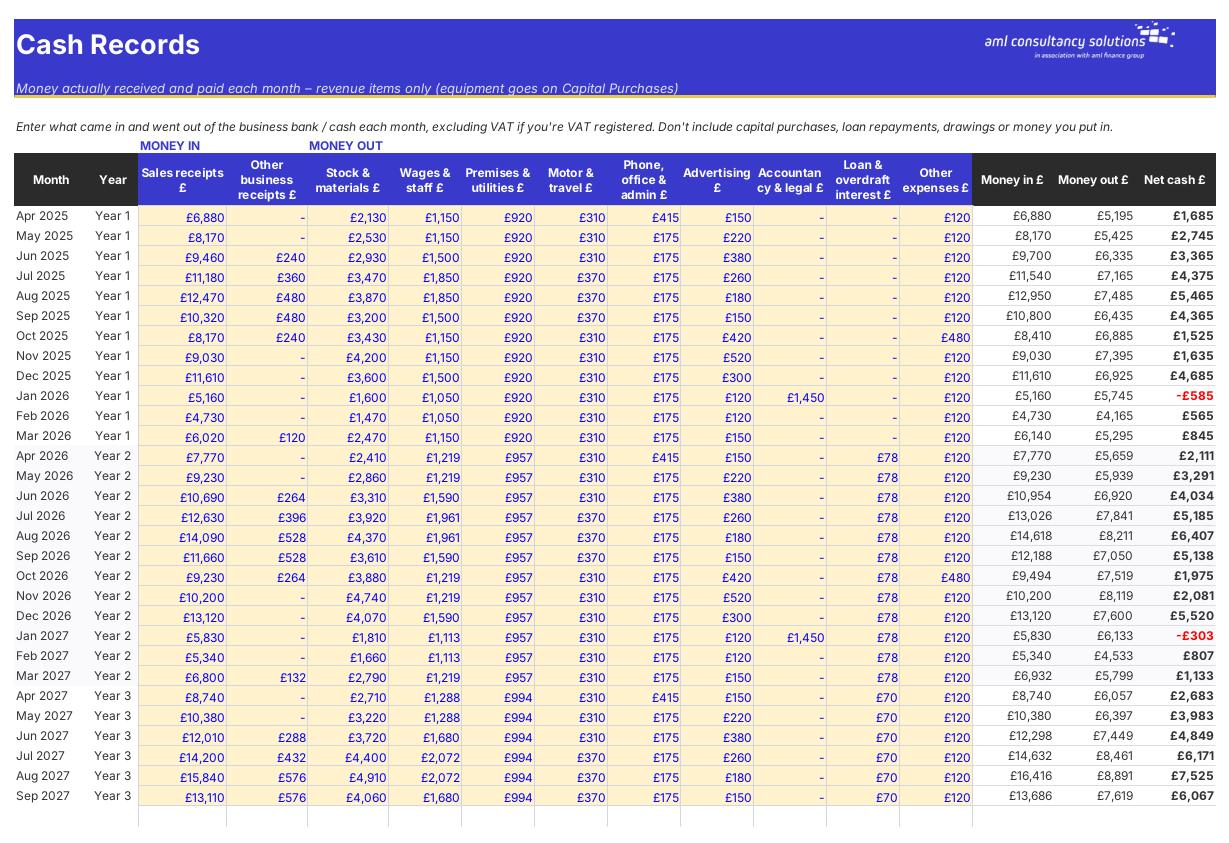
Money in and out for 36 months, with annual totals. What you do: enter monthly figures.
Step 2
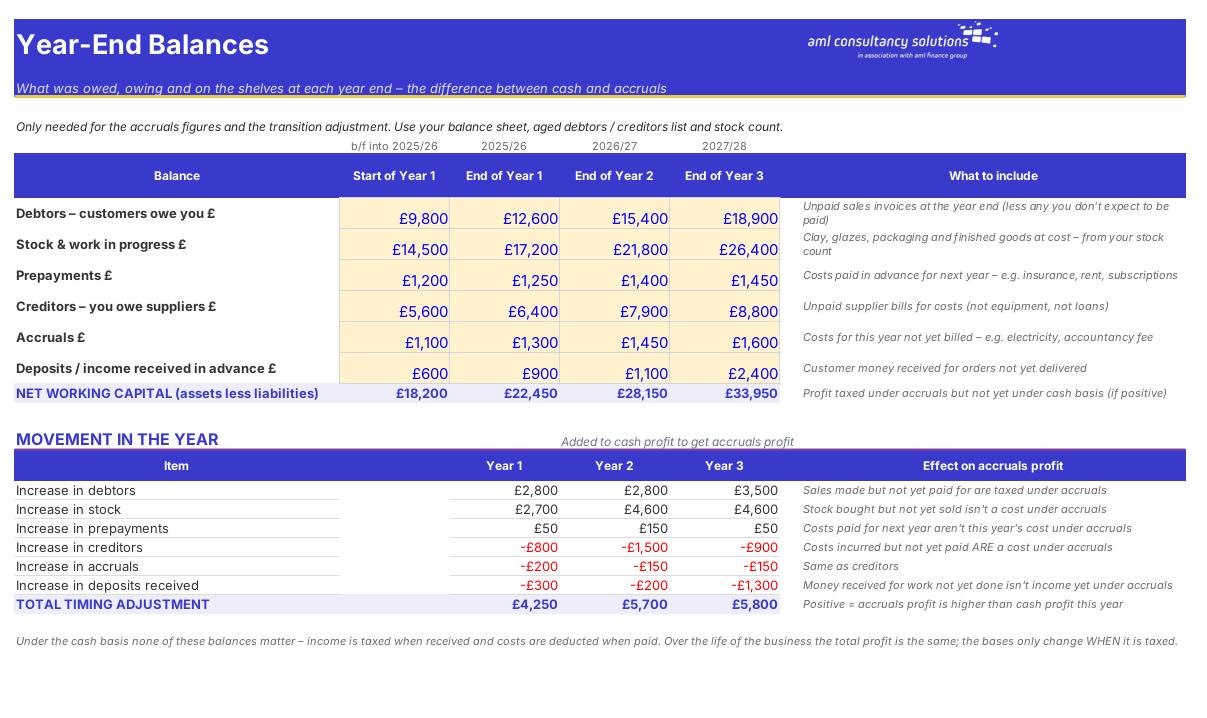
Debtors, stock, prepayments, creditors, accruals and deposits – and how they move each year. What you do: enter four columns of balances.
Step 3
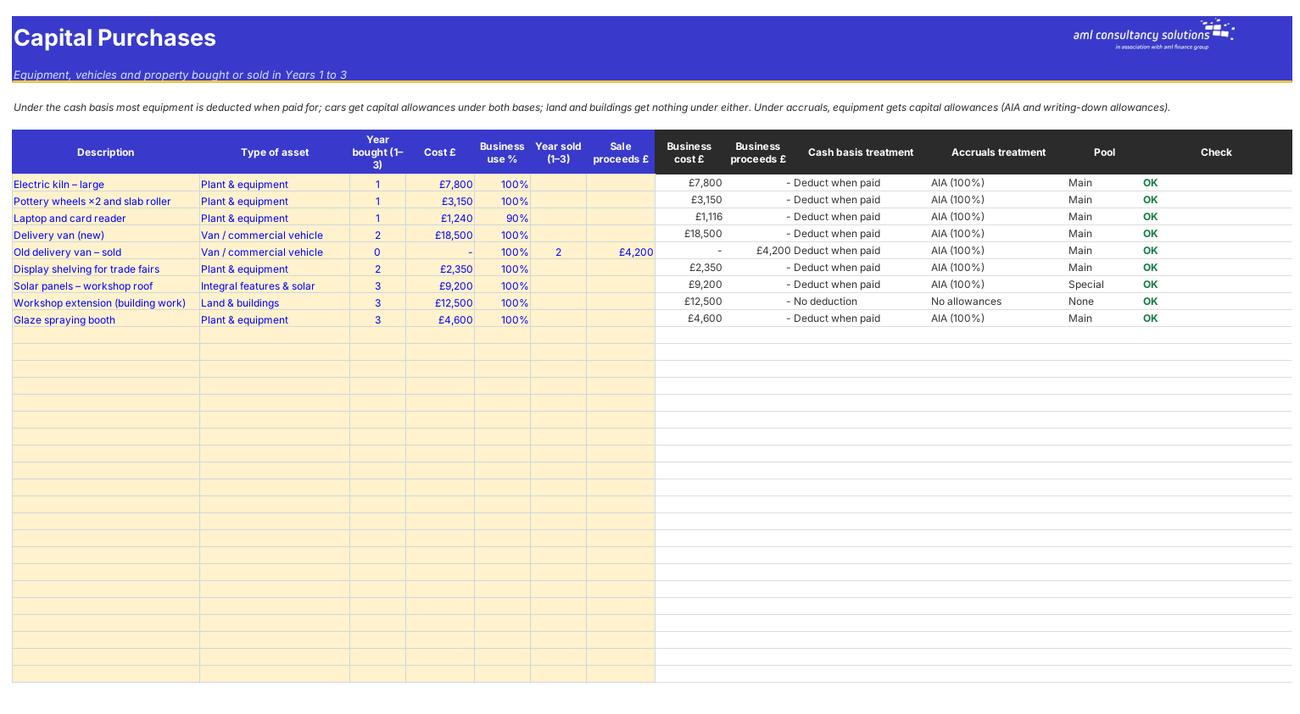
Assets bought or sold, with their treatment under each basis. What you do: one line per asset.
Step 4
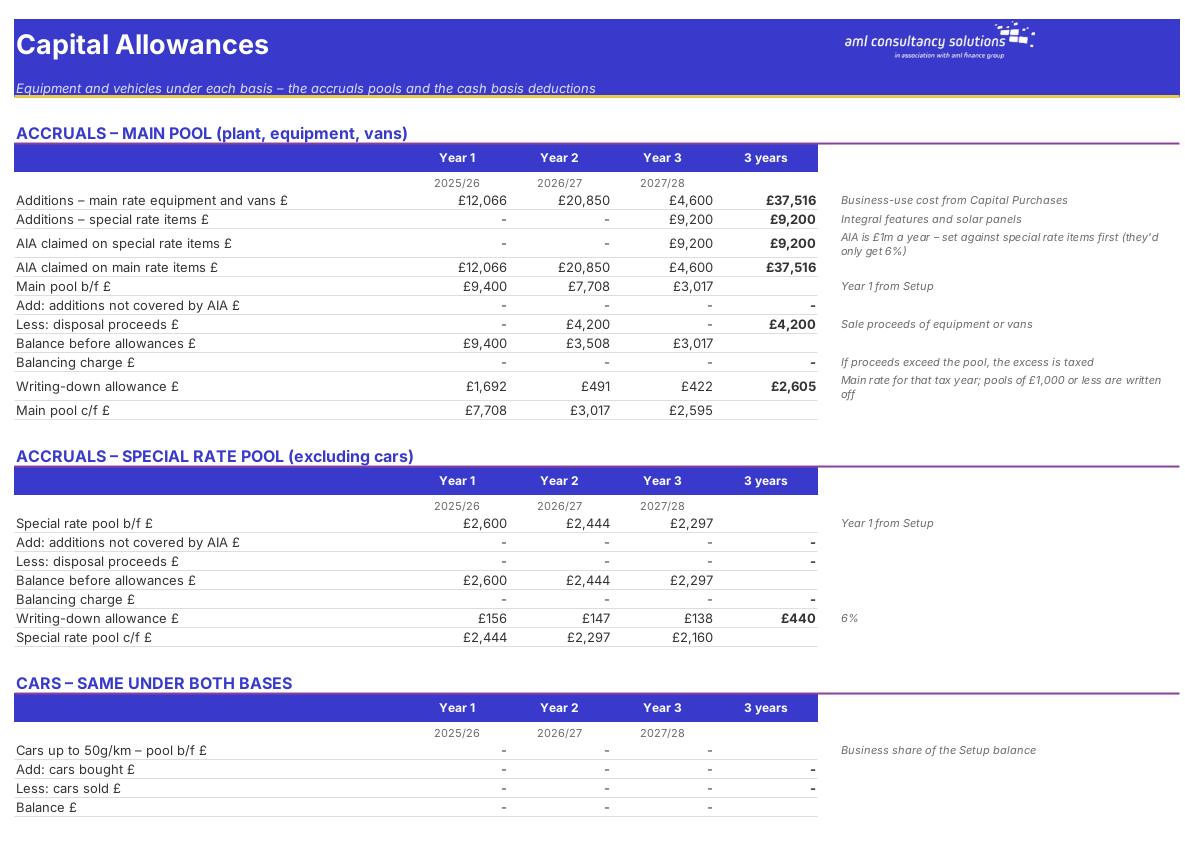
Accruals pools (main, special rate, cars) and the cash basis deductions. What you do: nothing – calculated.
Who it is for
Quick start
Your file is only released once payment has cleared.
You are taken to our secure checkout.
Checkout takes a minute and you get a receipt by email.
Your download link arrives as soon as payment clears.
We can adapt any prebuilt solution or build something bespoke, with a lifetime bug-free guarantee.
Part of AML Finance Group
Our sister firm, AML Accountancy Solutions, is an award-winning accountancy practice helping businesses and individuals across the UK with their accounts, tax, bookkeeping and payroll.
Visit AML Accountancy Solutions



