Standard VAT vs the Flat Rate Scheme – and whether to register
Secure checkout. Your download link is sent as soon as payment clears.
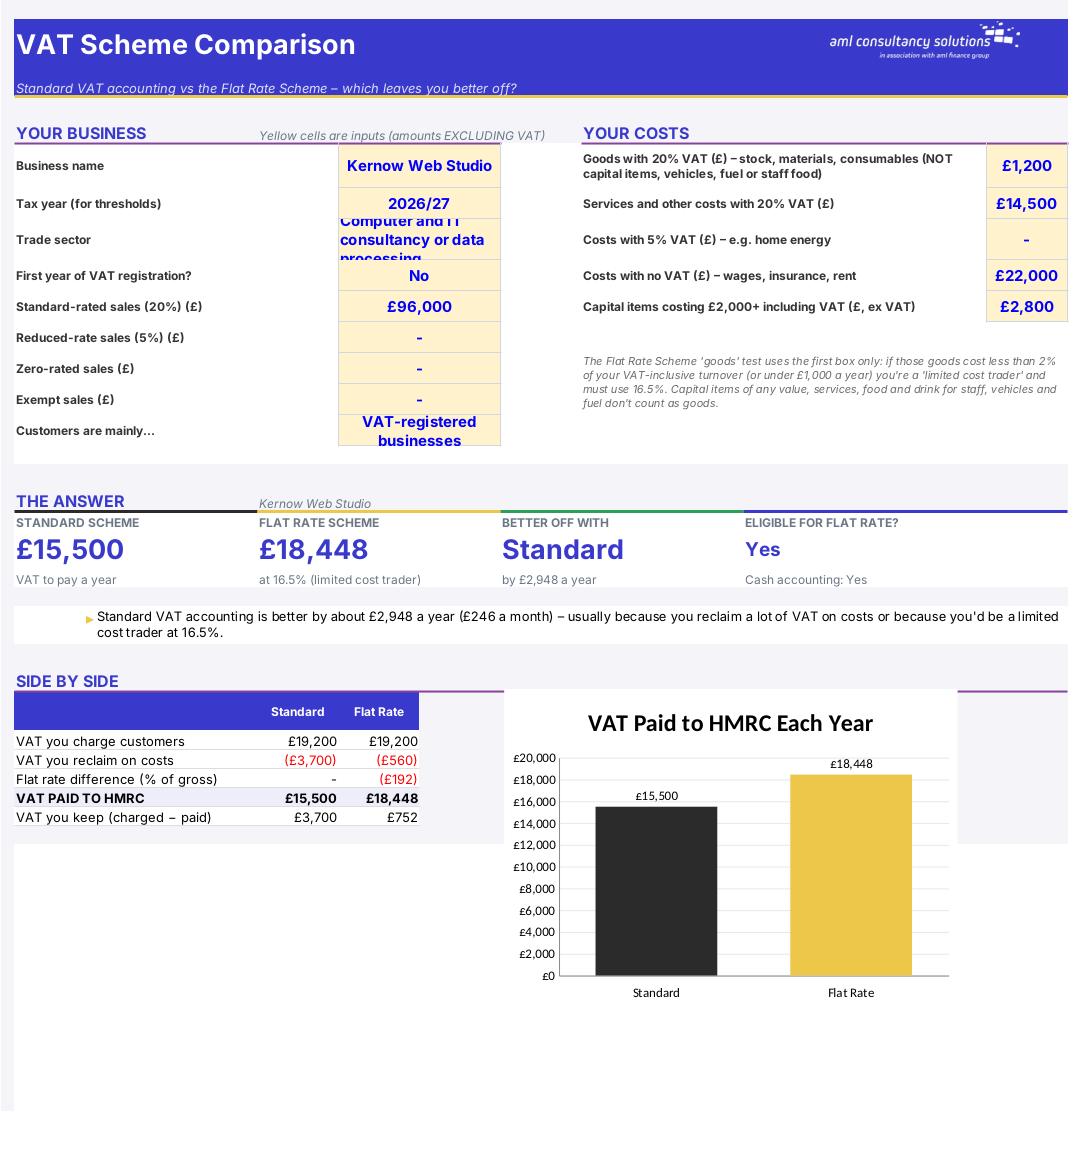
Once you're VAT registered you can account for VAT in more than one way. Under standard VAT accounting you pay HMRC the VAT you charge customers less the VAT you pay on costs. Under the Flat Rate Scheme you pay a fixed percentage of your VAT-inclusive turnover instead, and generally can't reclaim VAT on costs. Which is cheaper depends on your trade, how much you spend and on what – and the 'limited cost trader' rule catches many service businesses out. This workbook compares the two side by side, checks whether you can join the Flat Rate Scheme, and shows your profit if you were not registered at all.
See how it works
The sheets you will use most, in the order you will use them – shown with the sample data every workbook comes with.
Step 1
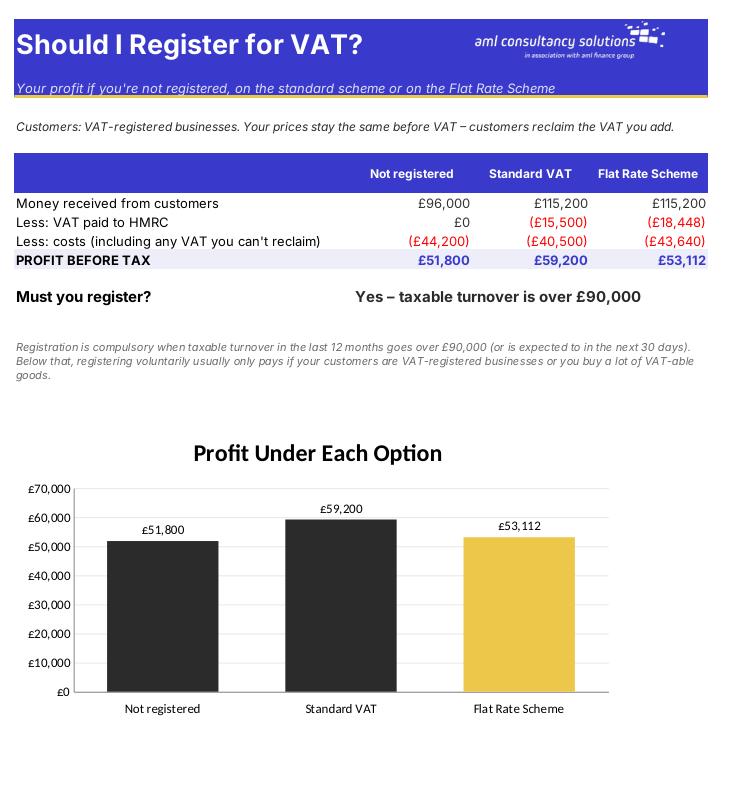
Profit under each option, whether registration is compulsory, and a chart. What you do: nothing to enter – it uses the Comparison inputs.
Step 2
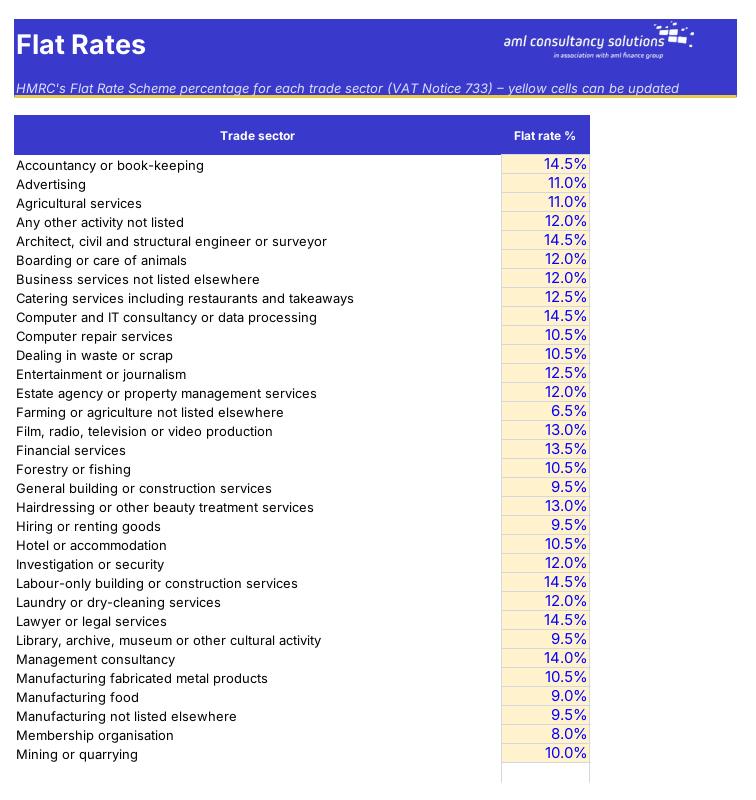
HMRC's flat rate percentage for each trade sector – this list feeds the Trade sector drop-down. What you do: normally nothing – update a yellow % if HMRC changes it.
Step 3
Step 4
Who it is for
Quick start
Your file is only released once payment has cleared.
You are taken to our secure checkout.
Checkout takes a minute and you get a receipt by email.
Your download link arrives as soon as payment clears.
We can adapt any prebuilt solution or build something bespoke, with a lifetime bug-free guarantee.
Part of AML Finance Group
Our sister firm, AML Accountancy Solutions, is an award-winning accountancy practice helping businesses and individuals across the UK with their accounts, tax, bookkeeping and payroll.
Visit AML Accountancy Solutions



